Launch providers say price-per-kilo model is over as Falcon 9 winds down
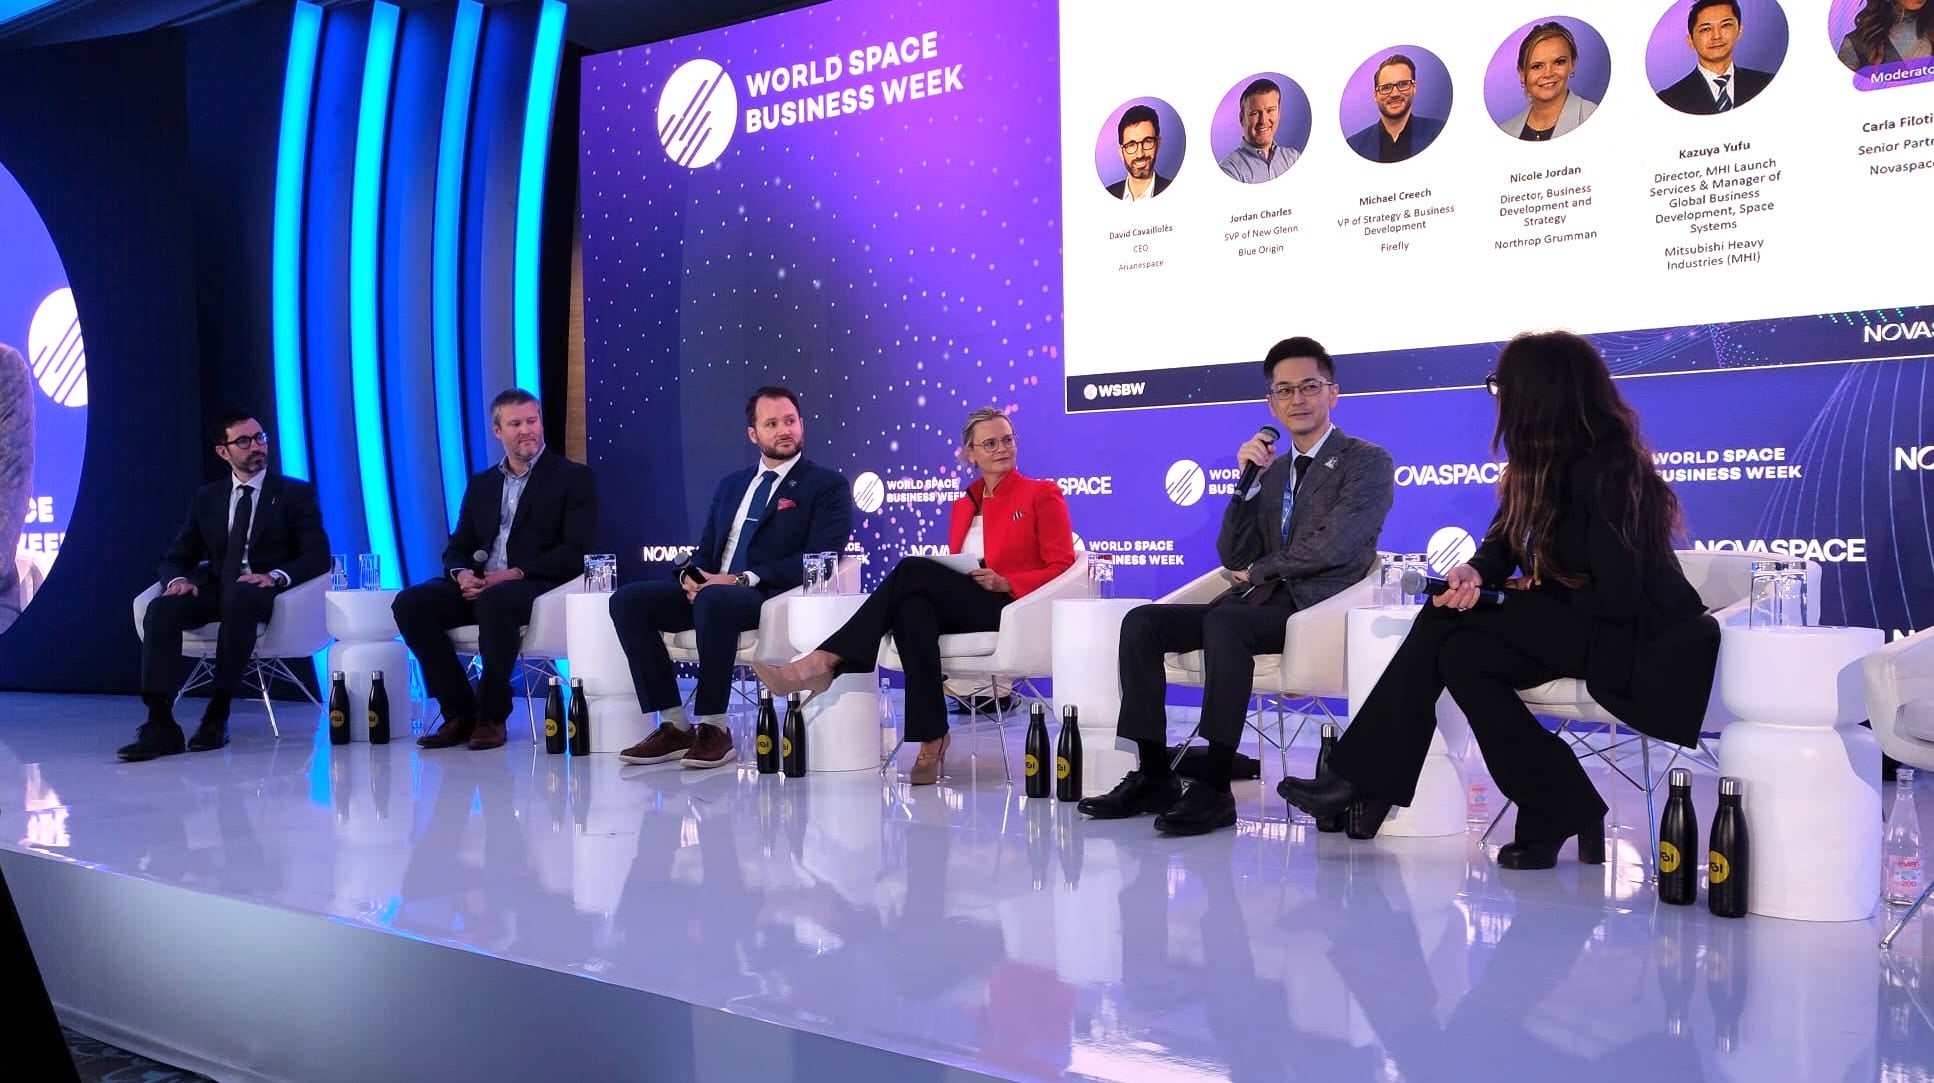
At World Space Business Week in Paris this week, senior leaders from Arianespace, Blue Origin, Firefly Aerospace, Northrop Grumman and Mitsubishi Heavy Industries (MHI) argued that the longstanding industry metric of price per kilogram is no longer a sustainable way to price orbital launches. The panel — held on Sept. 17, 2026 — framed the debate around two developments: a persistent supply shortage among non-SpaceX providers and statements from SpaceX leadership indicating a winding down of the Falcon 9 and Falcon Heavy programs.
Firefly Aerospace Vice President of Strategy Michael Creech stated that customers had become accustomed to "a high reliability and a low price, that frankly did not support the launch market." Creech described the ultra-low price-per-kilo model as "unsustainable" and predicted a market "reset" over the next six months to two years. He said the industry must move away from what he called "a race to the bottom on price" and toward business models that provide better revenue for launch providers.
Jordan Charles, senior vice president of New Glenn for Blue Origin, suggested that the metric of price-per-kilogram will become less central as launch cadence and orbital logistics mature. "If and when our cadence aspirations come true, the players on this stage 10 years from now [we] won’t be talking about price-per-kilogram — they’ll be talking about a whole different orbital logistics model," Charles said at the panel.
Nicole Jordan, director of Global Business Development and Strategy for Space Launch and Missile Defense at Northrop Grumman, agreed that price per kilogram had been a useful metric historically but reported that customers are now most concerned about risk and access to non-congested launch sites. That shift in customer priorities, panelists argued, will change how launches are priced and procured.
The discussion took place against a backdrop of SpaceX’s dominant market share. A BryceTech report cited at the session noted that SpaceX completed 165 orbital launches in 2025, representing nearly 51% of the global total, and that the company performed 43 commercial missions that year. The speakers did not include SpaceX leadership and only obliquely referenced remarks by Elon Musk earlier in the summer about winding down Falcon 9 and Falcon Heavy. Space Intel Report this week also said prospective SpaceX customers have been told the company is no longer accepting new commercial Falcon 9 reservations.
Panelists sought to reassure customers that their organisations are pursuing higher cadence and reliability. Blue Origin said it is rapidly ramping toward greater cadence for New Glenn; Firefly, Northrop Grumman and MHI described ongoing investments in vehicles and launch infrastructures intended to reduce supply bottlenecks and offer alternatives to customers reliant on a single dominant provider.
The panelists linked the pressure on price to the current supply shortage: Creech argued that rock-bottom launch prices allowed market entrants to undersell the true costs of providing reliable, repeatable access to orbit, leaving the sector fragile when demand patterns shifted. He and others said the result was a market distortion that now requires correction through higher prices, different commercial terms and new concepts of orbital logistics that may privilege schedule certainty and risk reduction over the cheapest per-kilogram bid.
Industry observers at the event also pointed to policy proposals that could affect demand and infrastructure. Press coverage noted recent White House ambitions for as many as 1,000 launches per year, but experts have questioned whether the current global launch infrastructure can scale to that level without significant investment. The panelists implicitly positioned their companies to capture demand should customers shift toward paying for access, redundancy and lower operational risk rather than the lowest possible kilogram price.
Context and historical perspective
The price-per-kilo metric became prominent during a decade when reusable launch vehicles and high manifesting for large constellations made aggressive pricing possible. For years, SpaceX’s Falcon 9 enabled lower costs and high cadence, reshaping customer expectations. Panelists at World Space Business Week argued that those expectations led to underfunded launch providers and a fragile market structure. The suggested reset echoes past periods in aerospace when technological shifts forced new commercial and contractual arrangements between launch providers and satellite operators.
Future implications
If the reset the panelists described arrives, satellite operators may face higher per-launch prices but gain improved schedule certainty, diversified suppliers and access to different orbital logistics solutions. New pricing models could reward guaranteed launch windows, dedicated launch sites, lower risk of postponement in congested ranges, and integrated mission services rather than lowest-cost mass rideshares. The panelists predicted that over a timeline of months to a few years the market will reorganise around these priorities.
How this relates to NovΔ mAInd's launch tracker
According to NovΔ mAInd's launch database, SpaceX has 143 launches tracked, a 99.3% success rate, first flight 2025-01-04, most recent 2026-09-17, and a payload capacity listed at 22800 kg to LEO; a Falcon 9 Block 5 mission (USSF-259) was scheduled for 2026-09-17 and it flew successfully into a polar orbit with SpaceX as operator.
The companies represented at the Paris panel are positioning themselves for a market where reliability, access and integrated logistics become primary selling points. The trajectory they outlined — away from price-per-kilo and toward diversified orbital logistics — will depend on how quickly alternative providers can scale operations and on whether customers are willing to trade lower short-term price for greater resilience and choice.